The Real Estate Room Team

Second Annual

Back to the Basics Homebuyer Workshop

Partner Educate Empower Build Our Community

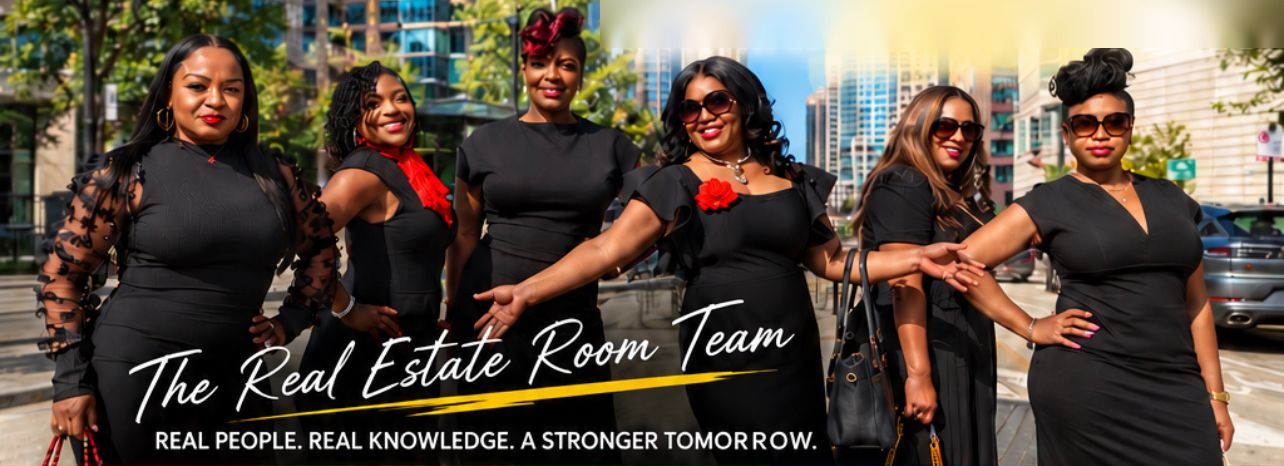
The six women of The Real Estate Room Team standing together in black dresses on a Chicago street, with the line: Real people. Real knowledge. A stronger tomorrow.
Save the dateNovember 7, 2026
Time1:00 PM to 4:00 PM
Learn the homebuying process
Explore financing options
Down payment assistance programs
Build & improve your credit
Get answers from real estate professionals

The Real Estate Room Team presents

Real people. Real knowledge. A stronger tomorrow.

Join us for an informative and engaging workshop designed to educate, empower, and connect future homeowners with trusted industry professionals.

Knowledge Today, Homeownership Tomorrow!

info@myrealestateroom.com www.myrealestateroom.com

Coldwell Banker logo Coldwell Banker Realty
The Real Estate Room Team

Featured speakers

  • Natasha Robinson Natasha RobinsonLoan Officer
  • Lamont Ellebb Lamont EllebbSecurity Expert ADT Home Security Services
  • Carshena Ross, Attorney at Law, since 2004 Carshena RossAttorney at Law
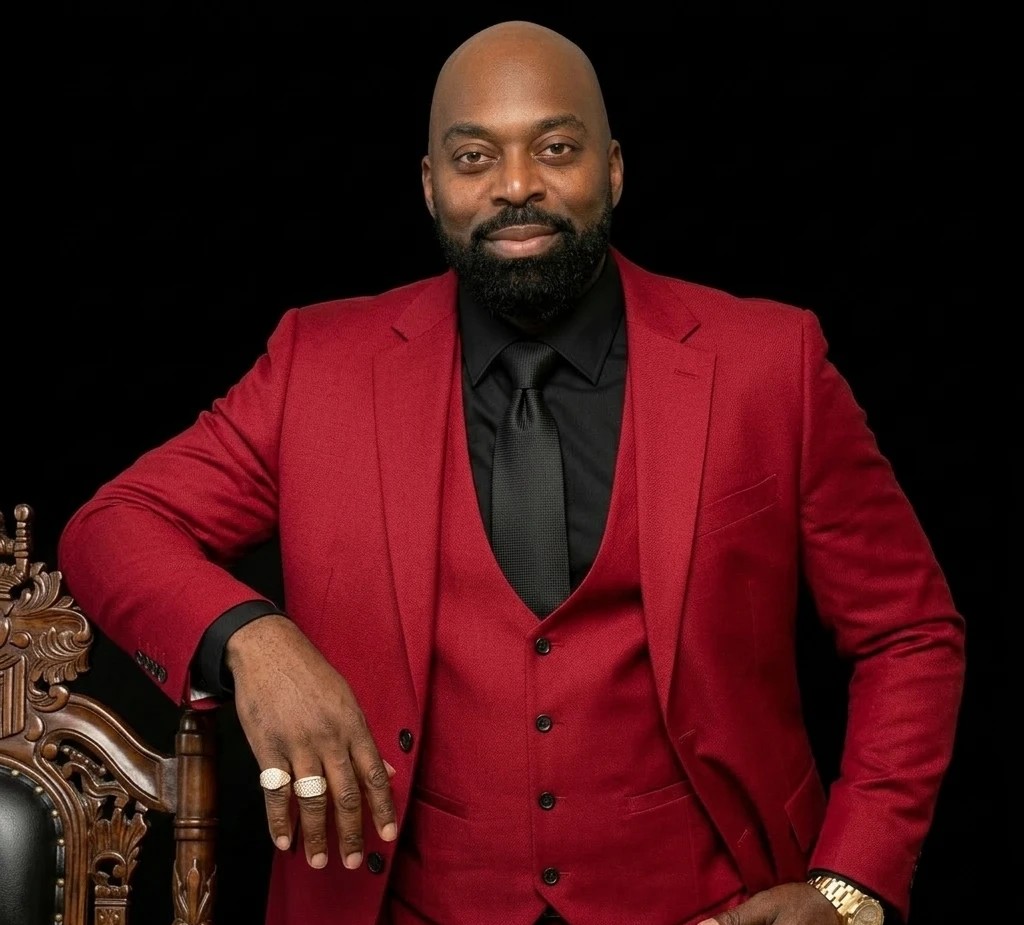
  • Jay Ford in a red three-piece suit Jay Got Me FundedCredit & Wealth Strategist Jay's session below
Jay Ford, founder of Jay Got Me Funded

Credit and funding session with Jay Ford

You don't start with the house. You start with the file a lender reads.

Everything Jay teaches at this workshop follows one plan: the WOLF Method. Wipe what shouldn't be there. Optimize what's left. Leverage it the right way. Then fund the goal.

  • 400+people helped with credit repair
  • $3.5M+in funding secured
  • 17people into their first home
  • 15property rental portfolio of his own
W

Step 1 of the WOLF Method

Wipe: dispute what's wrong on your report

Your report has to be accurate. If an item is wrong, incomplete, or can't be verified, you have the right to challenge it. Generic letters get generic answers, so find the real error first.

What you can dispute

  • Late payments
  • Collections
  • Charge-offs
  • Repossessions
  • Inquiries you didn't approve
  • Old names and addresses

What to look for

Pull all 3 reports from Experian, Equifax, and TransUnion at AnnualCreditReport.com. Then lay the same account side by side. Account numbers, balances, and dates should match. When they don't, you have something specific to dispute.

Sample only Same account, 3 different stories
Collection accountExperianEquifaxTransUnion
Account #...4471...4471...4417
Balance$842$1,120$842
Date opened03/202103/202106/2021
StatusCollectionCollectionCollection

Marked cells don't match. Those are the facts your dispute should name.

The dispute order

  1. 1Find inaccuraciesAccount numbers, balances, and dates across all 3 reports.
  2. 2Update personal infoCall all 3 bureaus first. Send a letter for names and addresses they didn't remove.
  3. 3Clear inquiriesTarget inquiries not attached to an open account. Call first, then send a letter.
  4. 4Freeze the 5Freeze the secondary bureaus listed below before your first round.
  5. 5Send round 1Dispute with all 3 bureaus, naming the exact errors you found.
  6. 6Track and escalateWatch the clock, save every letter, and escalate with a reason.

The clock after you dispute

What the Fair Credit Reporting Act requires of the bureau.

  1. Day 0Your dispute arrives. Send it by certified mail and keep the receipt.
  2. Day 30The bureau must finish its investigation. It can be 45 days in some cases, such as when you send more information during the 30 days.
  3. +5 business daysThe bureau must send you the written results.
  4. Next moveIf it was verified, ask how it was verified. The bureau has 15 days to answer. Then go to the company reporting it, or file a complaint with the CFPB.

How long items can stay on your report

Years, under the FCRA and common bureau practice. Past this, it's outdated and should come off.

  • Bankruptcy, Chapter 710
  • Bankruptcy, Chapter 137
  • Late payments7
  • Collections7
  • Charge-offs7
  • Repossessions7
  • Hard inquiries2

Wipe: your legal tools

The consumer laws behind every dispute

Quoting the right section tells them you know the rules. Here's what each law does and when to use it.

FCRAFair Credit Reporting Act
15 U.S.C. § 1681

Your main tool. It covers what the bureaus and the companies reporting to them have to do.

§ 1681e(b)
Bureaus must follow procedures for maximum possible accuracy.
§ 1681i(a)(1)
You can dispute. The bureau must investigate, generally within 30 days.
§ 1681i(a)(5)
If an item is inaccurate, incomplete, or can't be verified, it must be promptly deleted or corrected. It can't come back unless it's certified as accurate, and you must get notice within 5 business days.
§ 1681i(a)(7)
You can ask how an item was verified. They have 15 days to answer.
§ 1681c
Sets how long negative items can be reported.
§ 1681b
Your report can only be pulled for a permissible purpose. Use this for inquiries you didn't approve.
§ 1681s-2(b)
Once a bureau passes on your dispute, the company reporting the item must investigate too.
FDCPAFair Debt Collection Practices Act
15 U.S.C. § 1692

Use it with debt collectors.

§ 1692g
Dispute in writing within 30 days of their notice, and they must stop collecting until they send verification.
§ 1692e
Collectors can't make false statements, and they can't report credit information they know is false.
FCBAFair Credit Billing Act
15 U.S.C. § 1666

Use it for errors on credit card and other revolving account bills.

§ 1666
Send written notice within 60 days of the first bill showing the error. The creditor must investigate.
FACTAFair and Accurate Credit Transactions Act of 2003
Amends the FCRA

Use it for identity theft.

§ 1681c-1
Gives you the right to place fraud alerts on your file.
§ 1681c-2
With an identity theft report, bureaus must block the fraudulent items within 4 business days.

Which code goes with which item

Title 15 of the U.S. Code covers commerce, trade, and consumer protection. Find the item on your report, then start with these sections. All of them are in Title 15.

Accuracy and completeness

§ 1681e(b)
Bureaus must follow procedures for maximum possible accuracy.
§ 1681i(a)(5)
Inaccurate or unverifiable information must be removed or corrected.
§ 1692g
Validation of debts.
§ 1681b(a)(2)
Permissible purpose: a report can go out on your written instructions.

Open and late payments

§ 1666b
A card payment can't be treated as late unless statements go out at least 21 days before the due date.
§ 1692e
No false or misleading statements in collections.
§ 1681a(d)(2)(A)(i)
A report of only a company's own transactions with you isn't a consumer report.
§ 1681s-2(a)(1)(F)
COVID-19 relief: an account under a covered accommodation must be reported as current, or keep its earlier status. Doesn't apply to charged-off accounts.

Collections

§ 1692g
A collector must stop collecting until it validates the alleged debt.
§ 1692c
Limits when and how a collector can contact you.
§ 1681e(b)
Collections must be reported accurately across all bureaus.

Charge-offs

§ 1692g
If a collector has the debt, validation is required before it keeps collecting.
§ 1681c(a)(4)
Charged-off accounts can only be reported for 7 years.

Student loans

§ 1681e(b)
Student loans must be reported accurately across all bureaus.

Repossession

§ 1681b(a)(2)
Permissible purpose of the report.
§ 1692g
Validation of a repossession debt held by a collector.

Medical debt

§ 1692g
Validation of a medical debt held by a collector.

Inquiries

§ 1681b(a)(2)
Every inquiry needs a permissible purpose.

Public record: bankruptcy

Process
Freeze the 5 secondary bureaus and check the court record on PACER.

Public record: child support

§ 1681b
Lists when child support agencies can get your report.
§ 1681s-1
Sets how overdue child support gets reported. Use it when you ask for the method of verification.

Public record: eviction

§ 1681b
Permissible purpose of the report.
§ 1681
Congress's purpose for the FCRA: fair and accurate reporting.

Disputing and compliance

§ 1681s-2(a)(3)
A company can't keep reporting an item without noting that you dispute it.
§ 1681e(b)
Maximum possible accuracy in reporting.

The FDCPA sections (§ 1692) apply to debt collectors. They generally don't cover a creditor collecting its own debt.

Source: CFPB and the U.S. Code. This is education, not legal advice. For your specific case, talk to an attorney.

Wipe: before round 1

Freeze these 5 secondary bureaus

Lenders don't only look at Experian, Equifax, and TransUnion. These companies keep files on you too. Jay's strategy is to freeze them when you dispute, so fewer data sources can be pulled while your disputes run.

Clarity Services

Payday and installment loans, auto loans, check cashing, and rent-to-own. Owned by Experian.

Freeze online866-390-3118

LexisNexis

Public records, liens, judgments, bankruptcies, property data, and past addresses.

Freeze online800-456-1244

Consumer DataX

Payday and installment loans, subprime cards, and specialty loans. Listed by the CFPB as DataX, Ltd., owned by Equifax.

800-295-4790P.O. Box 740125, Atlanta, GA 30374

NCTUE

The National Consumer Telecom and Utilities Exchange: phone, pay TV, and utility accounts and payment history.

Freeze online866-349-5355

Bureau descriptions and contacts: CFPB list of consumer reporting companies and each company's freeze page, checked November 2026.

O

Step 2 of the WOLF Method

Optimize: know what makes up your score

A clean report is a start. Your score comes from 5 categories, and they don't count the same. Put your energy where the points are.

FICO score categories: payment history 35 percent, amounts owed 30 percent, length of credit history 15 percent, new credit 10 percent, credit mix 10 percent.
  • 35%Payment historyDo you pay on time? Keep every account current and dispute late payments that are wrong.
  • 30%Amounts owedHow much of your limits are you using? This is the fastest category to move.
  • 15%Length of historyHow old are your accounts? Keep old cards open when you can.
  • 10%New creditHow often do you apply? Too many hard inquiries at once looks risky.
  • 10%Credit mixDo you have both cards and loans? Lenders like to see you handle different types.

Source: myFICO. These are general weights for the population. Yours can vary.

Try it: your utilization

Add up your credit card balances and limits.

60% High

  • To get under 30% pay $1,550
  • To get under 20%, Jay's funding target pay $2,050
  • To get under 10% pay $2,550

Optimize: the profile you need for funding

A good score alone doesn't get you funded

Lenders look at fundability: how your whole profile lines up. Credit is the first door, fundability is the gate, and funding is the goal.

Credit Fundability Funding The first door The gate The goal

Your personal profile

0 of 10 done

Your business profile

0 of 10 done

Jay's funding-readiness targets. Every lender sets its own rules, and meeting these doesn't guarantee an approval. Your checkmarks stay on your device only.

One business, one story

Your name, address, and phone should match everywhere a lender checks. One mismatch can raise a flag.

Secretary of StateIRSDUNSExperian Business Same nameSame address and phone
L

Step 3 of the WOLF Method

Leverage: why tradelines matter

A tradeline is any account on your credit report. Good ones add positive payment history, available credit, and age, and those feed 3 of your 5 score categories. Build your own accounts first, then add authorized users.

  1. 7 to 10Primary accounts firstAccounts in your name. This is your base.
  2. 2 to 3Then authorized usersTypically ideal, depending on your budget and credit profile.

Start with these primary credit accounts

These are primary tradelines, accounts in your name, that help build your credit profile the right way.

Listed for education. Check each company's current fees and terms, and which bureaus it reports to.

What is an authorized user tradeline?

Strong tradeline Someone else's positive history 5-year historyPerfect payments$0 balance

An AU tradeline doesn't repair your credit. It can help your score by adding someone else's positive payment history to your report.

For example, if someone has a card with a 5-year history, perfect payments, and a $0 balance, they can add you as an authorized user, and that history is added to your report.

  • 30 to 100points it could potentially add, especially if your report has no recent negatives. Not guaranteed.
  • 14 to 21days after the statement date, when it typically reports
  • About 60days it typically stays on your report

What one good tradeline can do

Example: you owe $3,000. You're added to a card with a $10,000 limit and a $0 balance.

  • Before$3,000 of $5,00060%
  • After$3,000 of $15,00020%

Just the math, not a score promise. Your debt stayed the same, and your available credit went up.

Then apply the right way, in the right order

  1. 1Know your strongest bureauCompare all 3 reports. Find out which bureau each lender pulls.
  2. 2Check your profileRun the checklist above before an inquiry hits your report.
  3. 3Plan the orderKeep inquiries to 2 per bureau. Don't apply everywhere at once.
  4. 4If denied, ask whyThe Equal Credit Opportunity Act lets you get the specific reasons. Fix those first.
F

Step 4 of the WOLF Method

Fund: turn approvals into assets

An approval is just access. Know what the money is for before you apply, so it doesn't sit there or go to things that don't build anything.

  • Your first homeTalk with a loan officer, explore down payment assistance, and close on your own place.
  • A rental propertyBuy something that helps pay for itself.
  • A businessUse business funding so your personal savings can stay put.

A truck driver client of ours fixed his credit and got approved for a duplex. His tenant pays $2,000 a month. His mortgage is $2,400. That's the difference between a score and a plan.

Jay Ford, Jay Got Me Funded. Individual results vary.
  • $150Kbusiness funding for 1 client, $0 of their own savings used
  • $200Kapproval for a client after 3 banks said no
  • 33people into their new car

Knowledge Today, Homeownership Tomorrow!

Second Annual Back to the Basics Homebuyer Workshop

November 7, 2026 · 1:00 PM to 4:00 PM
10933 S. Eggleston Ave., Chicago, IL 60628